Why Loan Eligibility Isn’t the Same as Affordability
“Congratulations. Your In-Principle Approval has been granted.”
The couple sitting across from me were visibly relieved.
They had spent months thinking about their next property purchase, going through their finances and working out what kind of home they wanted. Now, they finally had an answer from the bank.
They could borrow up to $1.8 million.
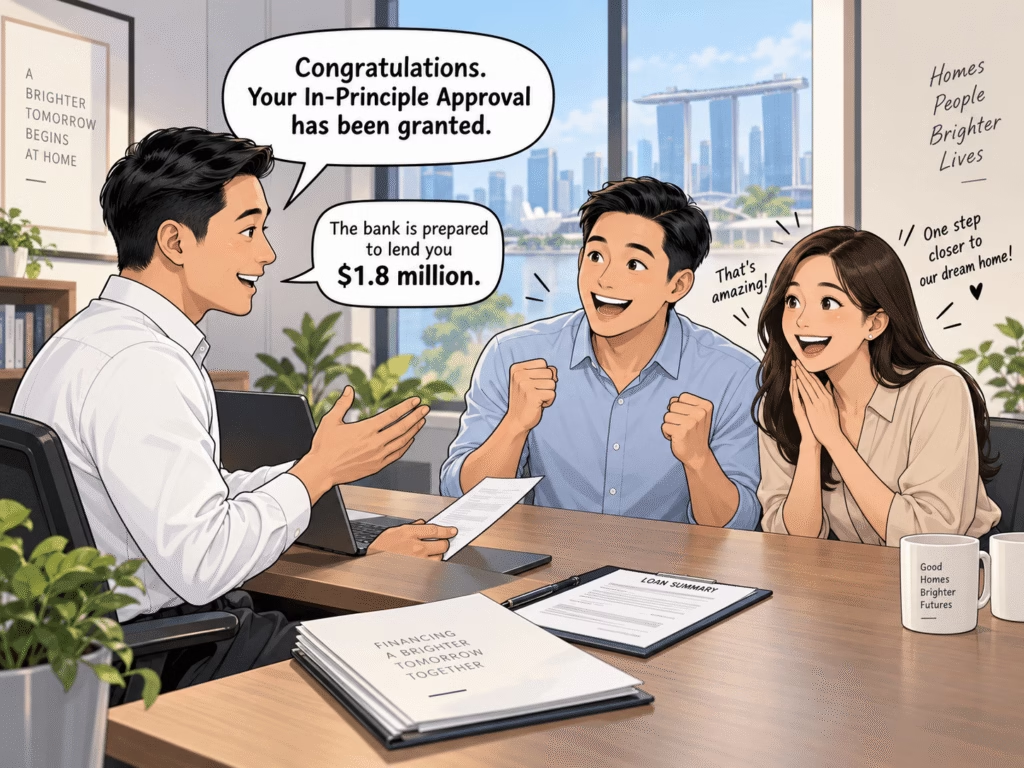
Naturally, they were excited. For many buyers, receiving an In-Principle Approval (IPA) feels like getting the green light to start searching for a property at the top end of the approved amount.
But before we started talking about properties, I asked them a different question:
“Do you actually want to borrow that much?”
They looked at me for a moment.
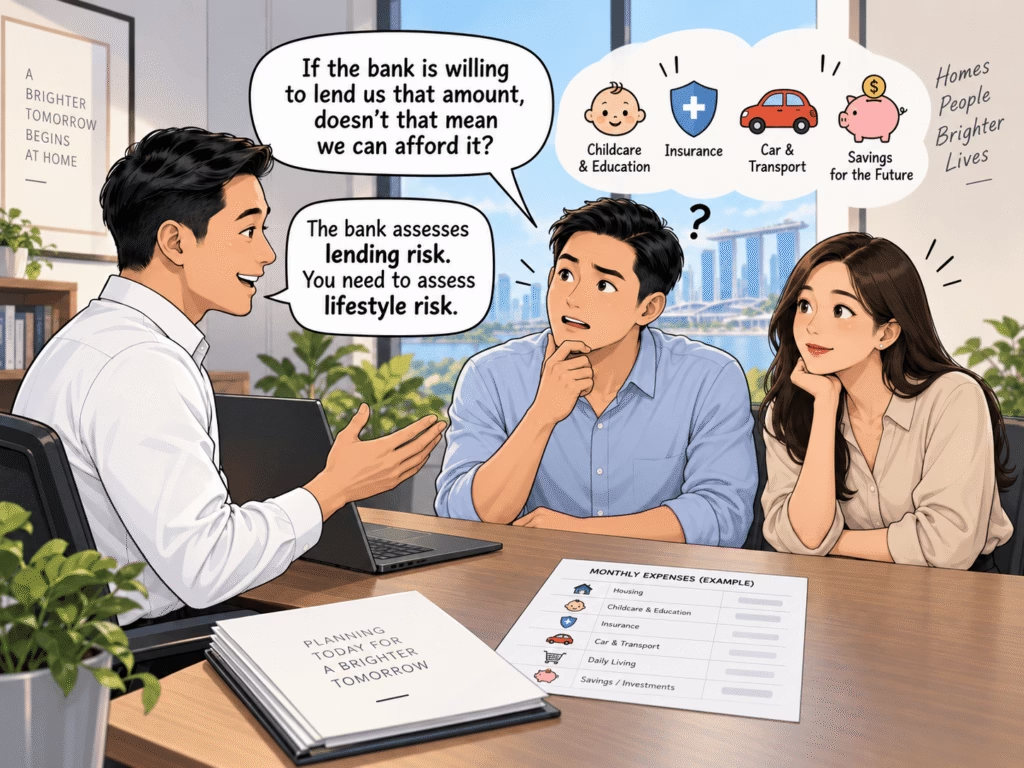
“If the bank is willing to lend us that amount,” the husband asked, “doesn’t that mean we can afford it?”
It is a perfectly reasonable question, and one we hear often. Banks do assess your income, existing debts and financial commitments before deciding how much they are prepared to lend. But a bank’s assessment answers one question:
How much are they comfortable lending you?
It does not necessarily answer another, equally important question:
How much are you comfortable paying every month for the next 20 or 30 years?
That difference matters.
Home Loan Affordability Is Not the Same as Loan Eligibility
Singapore’s borrowing rules, including the Total Debt Servicing Ratio (TDSR) and Mortgage Servicing Ratio (MSR), help determine whether a borrower meets certain financing limits.
They are important safeguards.
But they are not designed to tell you what kind of mortgage will feel comfortable for your household.
Two families earning the same income may have very different financial lives.
One may have young children, ageing parents to support and a car loan.
Another may have few commitments and substantial savings.
Both could technically qualify for the same mortgage amount, but that does not mean the same loan would suit both families.
Banks assess lending risk.
Homeowners also need to assess lifestyle risk.
The Lifestyle Test
Consider a couple with a combined monthly income of $18,000 who have been approved for a maximum home loan of $1.8 million.
At first glance, their finances may look strong.
But their monthly commitments could look something like this:
| Monthly Commitment | Amount |
|---|---|
| Mortgage Instalment | $7,100 |
| Parents’ Allowance | $1,000 |
| Childcare | $1,000 |
| Insurance | $1,000 |
| Car Expenses | $1,800 |
| Household Expenses | $2,500 |
| Investments & Savings | $1,000 |
Once everything is added together, the picture starts to look different.
A large portion of their income is already spoken for before discretionary spending even begins.
And life rarely stays exactly the same for 20 or 30 years.
- There could be another child.
- A parent may require more financial support.
- Someone may decide to change jobs or take a career break.
- Interest rates could change.
- There may be medical expenses, home repairs or simply a much-needed family holiday.
None of these things necessarily appear in a bank’s loan eligibility calculation.
But they matter when deciding how much mortgage debt you are comfortable carrying.
The Real Cost of Borrowing More
It is easy to underestimate the impact of increasing a home loan.
Suppose you are considering borrowing an additional $300,000.
Most buyers naturally look first at the difference in monthly instalment.
If the additional repayment works out to roughly another $1,000 or $1,200 a month, it may not seem significant relative to household income. But a mortgage is not a short-term commitment.
It can run for decades.
An extra $1,200 per month over 30 years represents $432,000 of cash flow before considering how the loan structure and interest rate may affect the final amount paid.
The bigger question, therefore, is not simply whether you can find another $1,200 each month. It is what else that money could have done for you.
- It could have gone towards your children’s education.
- It could have strengthened your emergency fund.
- It could have been invested.
- It could have supported your retirement planning.
- It could have paid for family experiences and holidays.
- Or it could simply have given you more breathing room every month.
The cost of taking on a larger mortgage is not only the interest charged by the bank.
There is also an opportunity cost.
Every additional dollar committed to your mortgage is a dollar that cannot be used somewhere else.
What Could an Extra $1,000 a Month Mean to You?
Over time, that money could contribute towards:
- children’s education;
- emergency savings;
- investments;
- retirement;
- family holidays;
- caring for parents;
- starting a business;
- or simply having more financial flexibility.
There is no universally correct answer.
Some buyers are perfectly comfortable allocating a larger portion of their income towards their home because property is a major personal priority.
Others would rather purchase something slightly more modest and keep more cash available for other goals.
What matters is understanding the trade-off before making the decision. A property purchase should not only make sense on the day you sign the Option to Purchase. Ideally, it should still feel manageable five, ten, and even twenty years later.
Questions We Encourage Buyers to Ask
“How much can I borrow?” is a useful starting point.
But before committing to a property, there are several other questions worth asking yourself:
✅ Will I still be able to save regularly after paying the mortgage?
✅ Could the household manage temporarily on one income?
✅ What happens if interest rates increase?
✅ Do I have enough emergency savings after paying the down payment and purchase costs?
✅ Can I continue supporting my parents or children comfortably?
✅ Will I still have room in my budget for travel, hobbies and the things I enjoy?
✅ Would this mortgage still feel manageable if my financial situation changed unexpectedly?
These questions are not meant to discourage anyone from buying a better or larger property.
They are meant to make sure the property fits comfortably into the rest of your life. That distinction often changes the way buyers approach their property search.
Instead of asking:
“What is the most expensive property I can buy?”
the conversation becomes: “What is the right property for the life I want to maintain?”
Maximum Budget vs Comfortable Budget
There is a useful shift in mindset that we encourage buyers to make.
Instead of thinking about your maximum loan, think about your comfortable loan.
Instead of focusing only on your maximum property budget, think about your sustainable property budget.
The two numbers may be the same. But very often, they are not.
And choosing not to stretch to the maximum does not mean you are being overly conservative. Sometimes it simply means you value flexibility.
Buying Bigger Isn’t Always Buying Better
There is understandable excitement around upgrading your home. Perhaps it means an additional bedroom, a better location, more space for your children, or a property you have always wanted.
There is nothing wrong with spending more on a home if it genuinely fits your finances and priorities.
The problem comes when the property begins to dictate everything else.
You may technically be able to afford the mortgage but find yourself constantly worrying about cash flow.
You may earn a good income but feel unable to take a career break.
You may own a beautiful home but hesitate every time your family plans a holiday.
That is why affordability should be measured by more than whether the monthly mortgage payment can be made. A home should ideally add to your quality of life, not quietly reduce it.
Coming Back to That Couple
A few months after our initial conversation, the couple contacted me again.
They had found a property.
But it was not at the maximum price they had originally been considering.
They decided to buy something slightly more modest than what their bank approval technically allowed.
During our conversation, one of them said:
“We realised we weren’t buying a smaller dream. We were buying more peace of mind.”
That stayed with me. They were still buying a home they genuinely liked.
The difference was that they could move in without feeling that every future financial decision would revolve around the mortgage.
There was still room to save.
Room to invest. Room to travel. And, importantly, room for the unexpected.
Final Thoughts
Buying a home is not a competition to see who can borrow the most.
A large loan approval can certainly create more options, but it does not mean you need to use every dollar available to you.
The right property is not necessarily the most expensive property you qualify for.
It is the one that fits your finances, your priorities and the kind of life you want to live after collecting the keys.
Financial flexibility is easy to overlook when you’re excited about buying a property. But once the mortgage becomes part of everyday life, that flexibility can become extremely valuable.
We rarely meet homeowners who complain that they have too much financial breathing room.
We do, however, speak to homeowners who wish they had left themselves a little more.
Because ultimately, the best measure of affordability is not simply how much a bank is prepared to lend you. It’s whether your mortgage still leaves you enough room to enjoy everything else you’ve worked hard for.
IQrate Mortgage Specialist’s Take
One of the first questions many buyers ask us is:
“How much can I borrow?”
And yes, it is an important number to know. But we believe the next question is even more important:
“How much am I genuinely comfortable borrowing?”
A well-planned home loan should let you keep building savings, invest for the future, and enjoy important milestones with your family.
The goal should not simply be to qualify for the biggest mortgage.
It should be to structure your property financing in a way that remains sustainable for years to come.
At IQrate, we help homeowners look beyond headline interest rates and maximum loan amounts so they can understand the full financial picture before deciding.
Because the right mortgage should help you own your home without letting your home own your finances.